Bridging Loans: How to Secure Auction Finance in 2026
Need to complete an auction purchase in 28 days? Discover how bridging finance works in 2026, current rates, and why a solid exit strategy is essential.
Bridging Loans: How to Secure Auction Finance in 2026
Introduction: The Auction Deadline Challenge
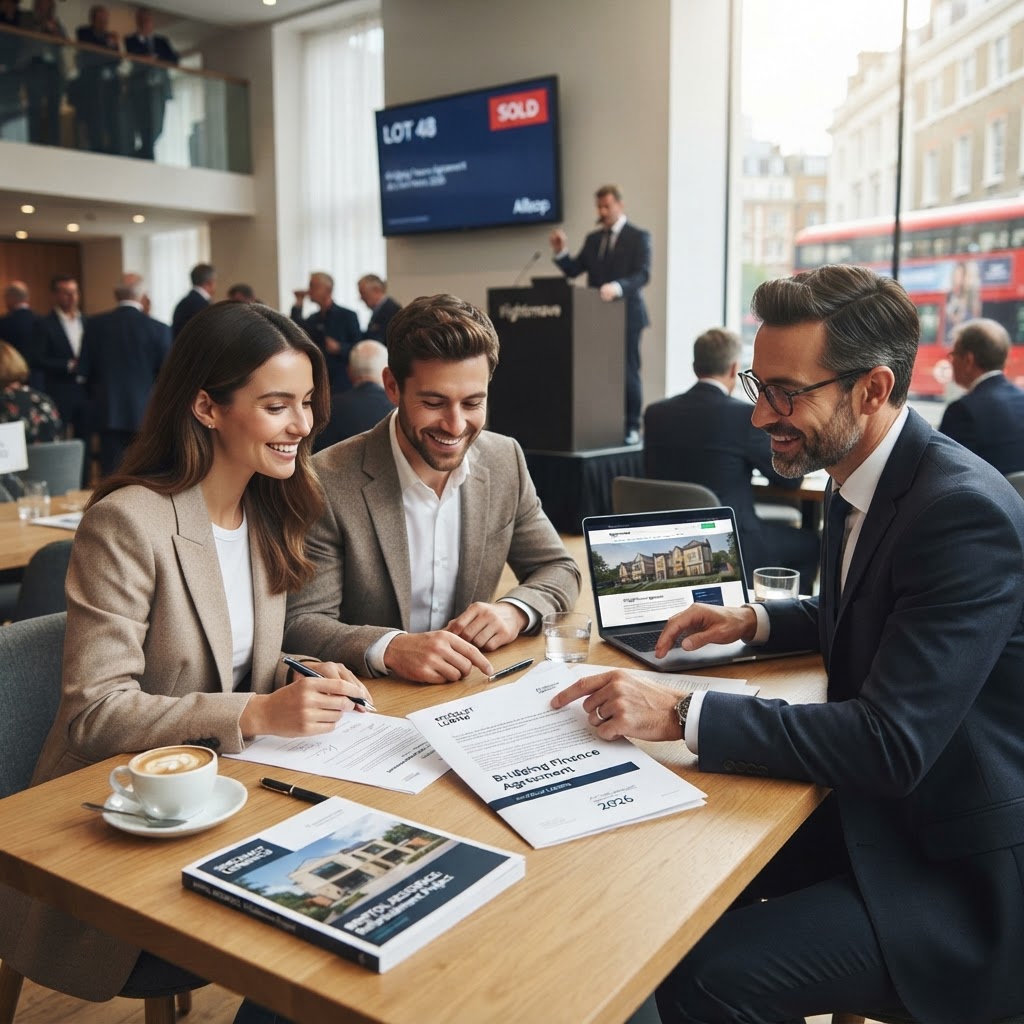
Securing a property at auction is an exciting milestone, but the strict 28-day completion deadline often leaves buyers scrambling. Traditional mortgage lenders typically require six to eight weeks for valuation and legal due diligence, creating a significant mismatch with auction timelines. This is where bridging finance acts as the essential engine for property investors and homebuyers alike.
In the current 2026 market, bridging loans provide the speed necessary to secure a purchase when mainstream lenders cannot move fast enough. Whether you are dealing with a broken chain, a refurbishment project, or a time-sensitive auction win, understanding how to package your application is critical. This guide explores how to navigate the process effectively while managing costs in a 3.75% base rate environment.
Understanding Bridging Finance in 2026
Bridging finance is a short-term, asset-backed loan designed to bridge the gap between a purchase and a long-term exit strategy. Unlike standard residential mortgages, these loans are underwritten primarily on the value of the security property and the viability of your repayment plan. As of late 2026, market average rates for bridging finance hover around 0.81% per month, though prime residential cases can start from approximately 0.55%.
Why Speed Matters
Most UK property auctions require completion within 28 days of the hammer falling. Because bridging lenders focus on the property's equity rather than lengthy income verification, they can often complete cases in two to four weeks. This speed is the primary reason investors use bridging to secure properties that would otherwise be lost to slow-moving traditional finance.
The Critical Role of Your Exit Strategy
Lenders care about one thing above all else: how you will repay the loan. A bridging loan is not a permanent solution, and you must have a concrete, evidenced plan to exit the facility. Without a clear strategy, your application will likely be declined, regardless of how much equity you have in the property.
- Refinancing: The most common exit, where you move the debt onto a standard buy-to-let or residential mortgage once the property is habitable or the auction purchase is complete.
- Property Sale: If you are refurbishing a property to sell, the sale proceeds act as your exit. Lenders will want to see evidence of the property's marketability and a realistic valuation.
- Capital Raising: In some cases, the sale of another asset or the receipt of inheritance can serve as the repayment vehicle, provided it is documented and verified.
Practical Guidance for Borrowers
When preparing your application, transparency is your greatest asset. Ensure you have your property details, a clear schedule of works if refurbishing, and proof of your deposit ready for the lender. In the current 2026 climate, lenders are rigorous about stress-testing your exit strategy against current market conditions, including the 3.5% CPI inflation rate and the 3.75% Bank of England base rate.
Remember that interest is typically charged monthly and can be 'rolled up' into the loan, meaning you do not necessarily need to make monthly payments. However, this increases the total amount borrowed, so factor this into your overall budget. Always work with a specialist broker who can access the full market and ensure your case is packaged to meet the specific criteria of lenders who understand your unique situation.
Next Steps
Bridging finance is a powerful tool, but it requires careful planning and expert guidance to ensure it is the right fit for your project. If you are considering an auction purchase or need to bridge a gap in your property journey, chat with Molly or speak to one of our specialist advisers today. We can help you assess your exit strategy and secure the right funding to meet your deadline.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.