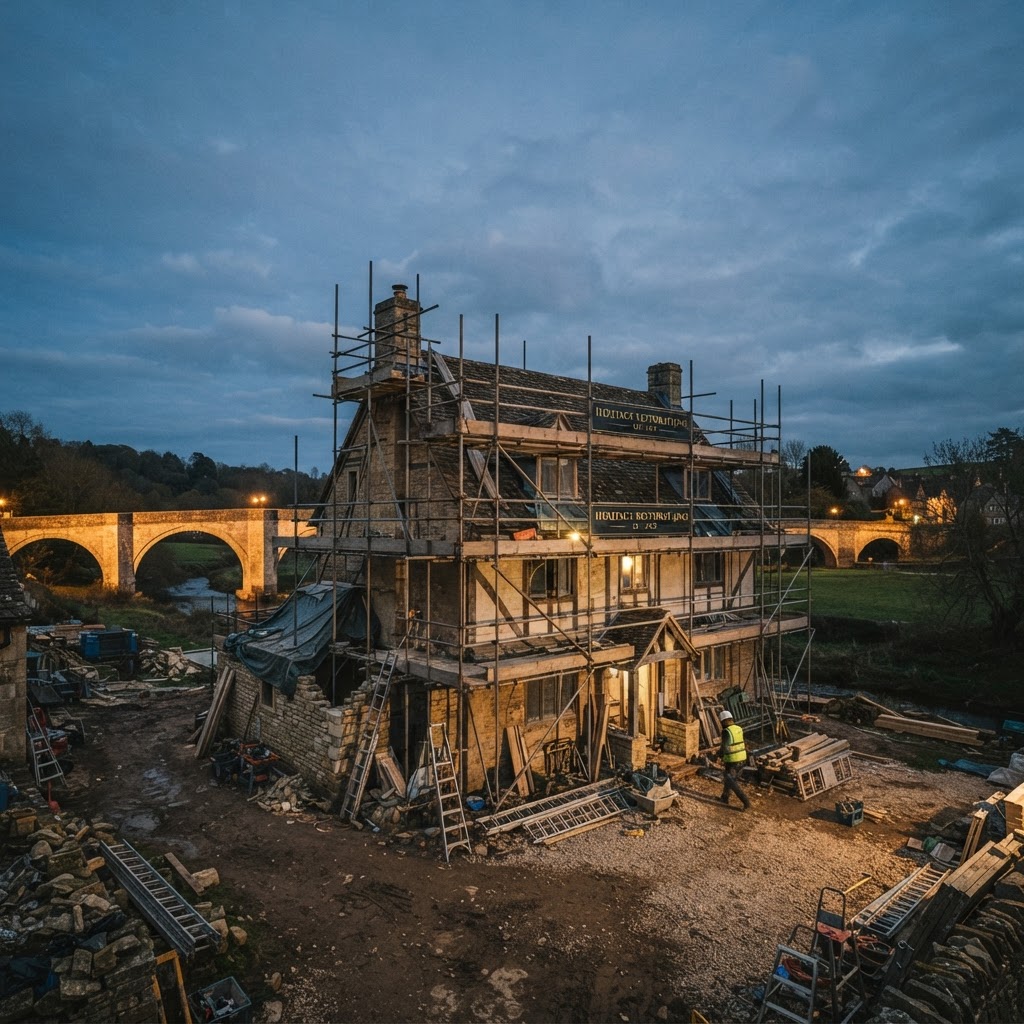
Short-term funding when time matters
Bridging Finance
Bridging finance is short-term borrowing secured against property, designed to bridge a gap — typically for 3–12 months. It's commonly used at auction, to break a property chain, or to refurbish a property before refinancing to a term mortgage.
Will your deal repay the bridge?
Bridging needs a credible exit. Use our free HMO Deal Appraiser to check whether the finished property will support a refinance that repays the loan — and recycles your capital — before you commit.
- No sign-up needed
- Live figures as you type
- Send the deal to an adviser
Tailored advice for your situation
What bridging finance is for
Bridging finance is short-term, secured lending designed to bridge a funding gap until a longer-term solution is in place. It's commonly used at property auctions (where completion must happen within weeks), to break a chain when your buyer pulls out, or to fund refurbishment before refinancing onto a standard mortgage.
Because bridging is short-term and secured against property, lenders focus on the value of the property and your exit strategy — how you'll repay the loan — rather than your affordability alone. This makes it flexible, but it's more expensive than a term mortgage and needs a clear, realistic exit.
The exit strategy — how you repay the loan
Every bridging loan needs a credible exit strategy. The two most common are selling the property (for a flip or a downsizer) or refinancing onto a term mortgage once refurbishment is complete or a sale has gone through. Lenders will want evidence that your exit is achievable.
We'll help you stress-test your exit before you commit: has the refurbishment budget been accurately costed, is the refinancing achievable at the expected property value, and is there a fallback if timing slips? A clear exit keeps costs down and risk low.
- Sale of the property (flip, downsizing, or chain resolution)
- Refinance onto a term mortgage after refurbishment
- Sale of another property in the background
Costs, rates, and when bridging makes sense
Bridging rates are typically charged monthly rather than annually, with arrangement fees, valuation fees, and legal costs on top. Despite the higher cost, bridging can save money overall when it secures a property deal that would otherwise fall through, or enables a refurbishment that adds significant value.
It's not a substitute for a long-term mortgage. We'll compare it against alternatives — like a let-to-buy, a product transfer, or a specialist term mortgage — so you only use bridging where it genuinely makes financial sense.
Common Questions
Based in Colchester. Helping clients across the UK.
Mortgage321 provides advice by phone, video and WhatsApp, so you don’t need to visit an office.
Related Mortgage321 Cases
Want Matthew to look at your circumstances?
You don't need to work out which lender or mortgage route you need. Tell Matthew what you're trying to achieve and he'll identify what needs investigating.