Bridging Loans Explained: A 2026 Guide for UK Borrowers
Need fast property finance? Discover how bridging loans work in 2026, current monthly rates, and why a solid exit strategy is essential for your application.
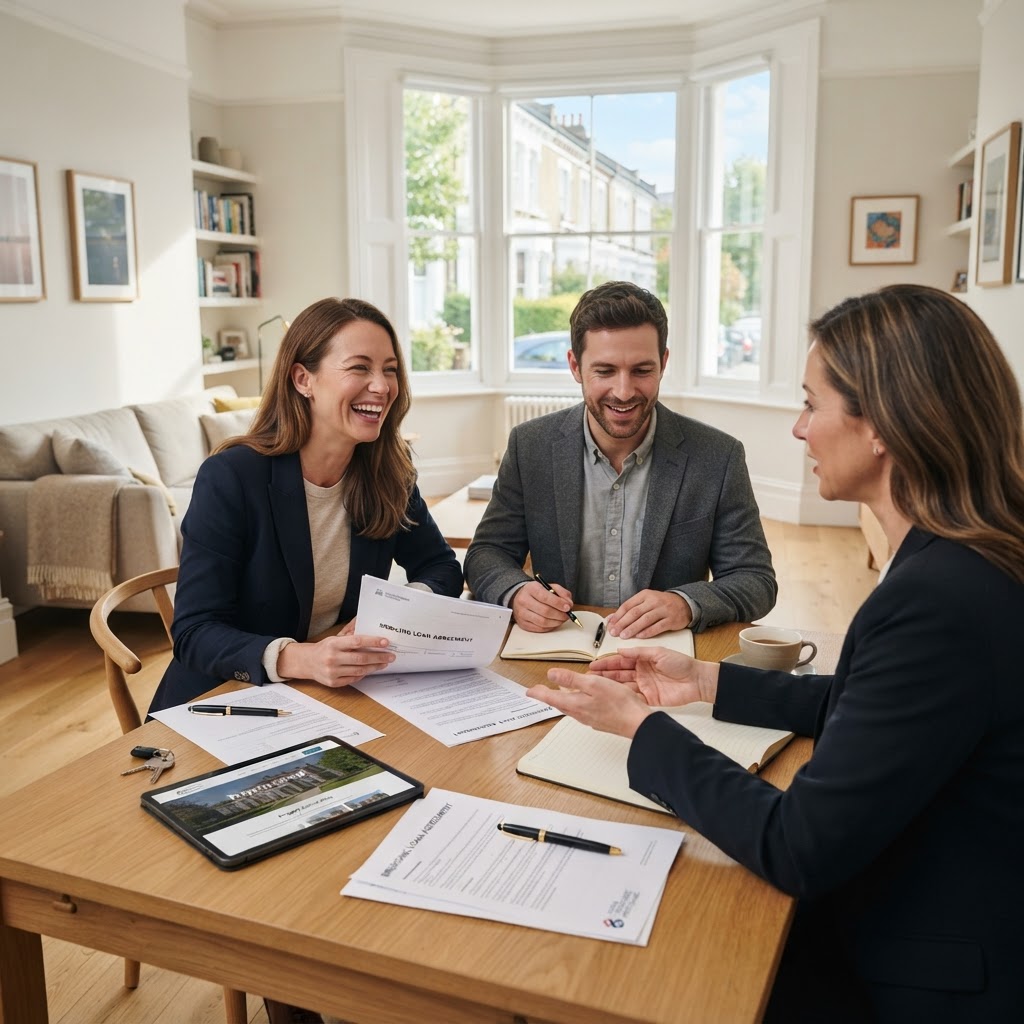
Bridging Loans Explained: A 2026 Guide for UK Borrowers
Introduction: Bridging the Gap in Today's Market
In the fast-paced UK property market of 2026, timing is often everything. Whether you are buying at auction, navigating a broken property chain, or securing a renovation project, you may find yourself needing capital faster than a traditional mortgage allows. This is where a bridging loan can provide the necessary liquidity to keep your plans on track.
Bridging finance is a short-term, secured loan designed to cover a temporary funding gap. Unlike standard mortgages, which are built for long-term stability, these loans are engineered for speed and flexibility. In this guide, we explore how these products function, the costs involved, and the critical importance of your exit strategy.
With the Bank of England base rate currently at 3.75% and inflation at 3.1%, understanding the cost of borrowing is more important than ever. While bridging loans offer a vital lifeline, they are a specialist financial tool that requires careful planning and professional advice to ensure they align with your broader financial goals.
How Bridging Loans Work
At its core, a bridging loan is secured against property, such as your home or an investment asset. Because they are short-term—typically lasting from 3 to 18 months—they are not intended to be a permanent solution. Instead, they act as a bridge until a longer-term finance arrangement, such as a standard mortgage or the proceeds from a property sale, becomes available.
One of the most important aspects of any bridging application is your exit strategy. Lenders will not approve a loan without a clear, realistic plan for how you intend to repay the debt. Common exit strategies include selling the property you are bridging against or refinancing onto a long-term buy-to-let or residential mortgage once the project is complete.
The Application Process
Bridging loans are known for their speed, with some lenders able to issue a decision in principle within hours. However, the full process usually takes two to three weeks to account for necessary legal work and property valuations. The steps generally include:
- Initial Assessment: The lender reviews your exit strategy and the value of the security property.
- Valuation and Legal: A professional valuation is conducted, and solicitors handle the title searches and loan conditions.
- Completion: Once all conditions are satisfied, the funds are drawn down, allowing you to proceed with your purchase or project.
Understanding Costs and Rates
Bridging loan interest is typically quoted as a monthly rate rather than an annual percentage rate (APR). As of late 2026, typical rates range from 0.55% to 1.50% per month, depending on your loan-to-value (LTV) ratio, the complexity of the deal, and your credit profile. For example, a £300,000 loan at 0.75% per month would generate approximately £2,250 in interest each month.
Beyond the headline interest rate, you must account for additional fees that can impact your total cost of borrowing:
- Arrangement Fees: Usually 1.5% to 2.0% of the loan amount, covering the setup of the facility.
- Exit Fees: Some lenders charge a fee if the loan is repaid early, though many waive this.
- Valuation and Legal Fees: These are standard costs associated with securing any property-backed loan.
Practical Considerations for Borrowers
When considering a bridging loan, it is vital to model your costs accurately. Because interest is often "rolled up"—meaning it is added to the loan balance and paid at the end of the term—the total amount owed will grow over time due to compounding. Always ensure your exit strategy has a buffer for potential delays in property sales or planning permissions.
- LTV Limits: Most lenders cap borrowing at 70% to 80% of the property value. A lower LTV often secures a more competitive monthly interest rate.
- Open vs. Closed Bridges: A closed bridge has a fixed repayment date (e.g., you have already exchanged contracts on a sale), while an open bridge is more flexible but often carries a higher interest rate.
- Professional Advice: Given the specialist nature of these loans, working with a broker who understands the current 2026 market is essential to finding the right lender for your specific circumstances.
Next Steps
Bridging finance can be a powerful tool, but it is not suitable for every situation. If you are considering a short-term loan to facilitate a property purchase or renovation, it is essential to discuss your plans with an expert. Chat with Molly or speak to one of our experienced advisers today to receive a personalised assessment of your options and ensure your strategy is robust.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.