Bridging Loans for Property Refurbishment: A 2026 Guide
Unlock property potential with bridging finance. Learn how to fund light or heavy refurbishments, manage LTVs, and secure your exit strategy in 2026.
Bridging Loans for Property Refurbishment: A 2026 Guide
Introduction: Unlocking Property Potential
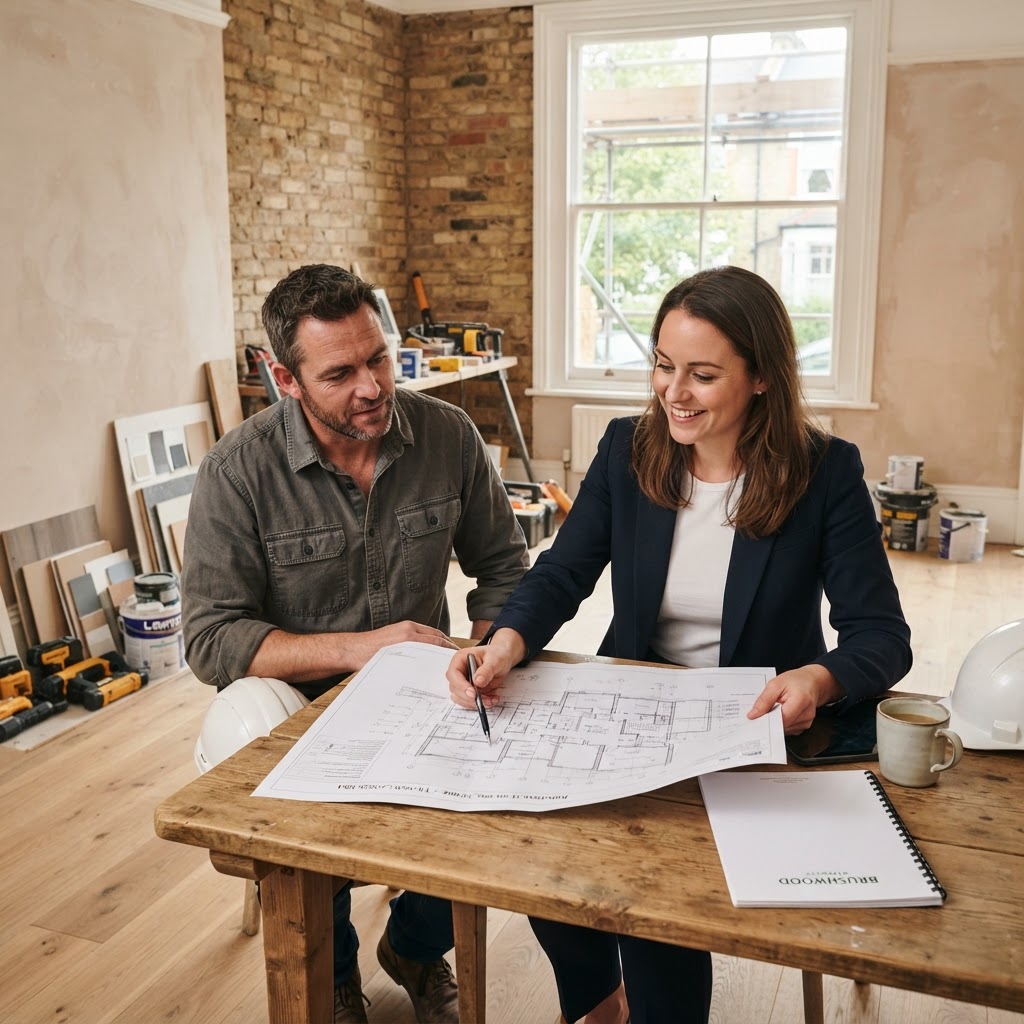
For property investors and landlords, finding a property that needs work is often the best way to add significant value. However, traditional mortgages are rarely suitable for properties that are unmortgageable or require extensive structural changes. A refurbishment bridging loan provides the short-term capital needed to purchase and renovate, allowing you to move quickly in a competitive market.
Whether you are planning a light cosmetic refresh or a heavy structural conversion, understanding how to structure your finance is critical. With the Bank of England base rate at 4.00% and inflation at 3.5%, investors are increasingly looking for ways to maximise yields through value-add projects. This guide explores how to navigate the current bridging landscape to ensure your project remains viable.
Light vs. Heavy Refurbishment: Knowing the Difference
Lenders categorise projects based on the scope of work, which directly impacts your interest rate and loan-to-value (LTV) limits. Distinguishing between these two categories is the first step in your application.
Light Refurbishment
Light refurbishment typically involves cosmetic improvements that do not require planning permission or structural changes. This includes new kitchens, bathrooms, flooring, and redecoration. Because these projects are lower risk, lenders often offer more competitive rates, with some products starting from approximately 0.53% to 0.65% per month depending on your LTV.
Heavy Refurbishment
Heavy refurbishment involves structural work, such as loft conversions, extensions, or changing a property's use (e.g., converting a house into an HMO). These projects require planning consent and building regulations approval. Lenders view these as higher risk, meaning rates are typically higher, often ranging from 0.80% to 1.5% per month, reflecting the complexity and oversight required.
Key Considerations for Your Project
- Exit Strategy: Lenders require a clear, credible exit route, such as refinancing onto a long-term buy-to-let mortgage or selling the property upon completion. Having your exit plan documented early is essential for approval.
- Loan-to-Value (LTV) Limits: Most lenders offer up to 75% LTV on the current market value. If you have additional property, some lenders may allow you to use it as extra security to reach up to 100% of the purchase and works costs.
- Valuation Speed: In 2026, speed is often determined by the valuation process. While some lenders use Automated Valuation Models (AVMs) for standard properties, complex or heavy refurbishment projects will require a physical surveyor inspection, which should be factored into your timeline.
- Drawdown Methods: For light works, some lenders release the full facility at completion. For larger projects, funds are often released in stages, supported by monitoring to ensure the work is progressing according to your schedule.
Practical Guidance for Investors
When approaching a lender, ensure you have a detailed schedule of works. This document should outline the costs, the timeline, and the projected Gross Development Value (GDV). Lenders will assess your ability to manage the project, so highlighting your experience—or the experience of your contractors—can significantly improve your chances of securing favourable terms.
Remember that bridging finance is a short-term tool, typically lasting 6 to 24 months. The goal is to increase the property's value sufficiently to refinance or sell, effectively 'bridging' the gap between the purchase and your long-term financial goal. Always account for the arrangement fees and interest costs in your initial budget to ensure the project remains profitable.
Next Steps
Every refurbishment project is unique, and the right lender for your specific situation can make all the difference in your project's profitability. If you are considering a property renovation and want to discuss your funding options, chat with Molly or speak to one of our specialist advisers today for personalised guidance.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.