HMO Mortgages: Navigating Specialist Lending in 2026
Investing in HMOs in 2026? Discover how to navigate complex licensing, rental stress tests, and specialist lender criteria to secure your multi-let property.
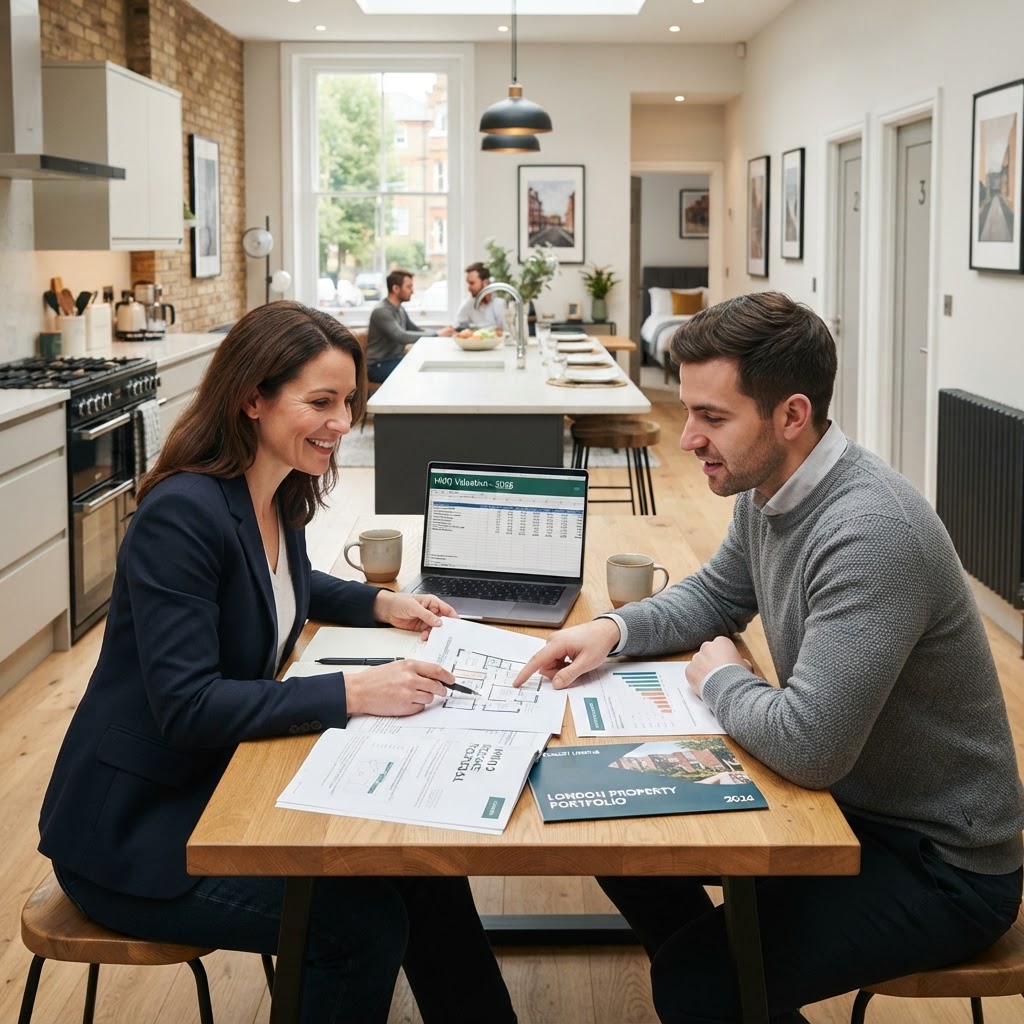
HMO Mortgages: Navigating Specialist Lending in 2026
Introduction: The Reality of Multi-Let Investment
Investing in Houses in Multiple Occupation (HMOs) remains a powerful strategy for landlords seeking higher gross yields compared to standard single-let properties. However, as of November 2026, the financing landscape has become increasingly nuanced, requiring a sophisticated approach to lender selection and compliance.
Whether you are converting a property or expanding an existing portfolio, understanding how lenders assess risk is critical. With the Bank of England base rate at 4.00% and inflation at 3.5%, lenders are applying rigorous stress tests to ensure your rental income can withstand potential market shifts.
This guide explores the specific hurdles landlords face today, from mandatory licensing requirements to the intricacies of Interest Coverage Ratios (ICR). We focus on how to position your application to meet the exacting standards of specialist lenders in the current economic climate.
Understanding Lender Appetite for HMOs
Not all lenders view HMOs the same way. While mainstream buy-to-let providers often shy away from multi-tenancy risks, specialist lenders recognise the income potential of these assets. They typically look for evidence of professional management and robust property standards.
Key Criteria for Approval
- Licensing Compliance: Mandatory licensing applies to properties with five or more occupants from two or more households. Many local authorities have also introduced additional or selective licensing schemes for smaller HMOs, which lenders will verify before issuing an offer.
- Rental Stress Tests: Lenders apply an Interest Coverage Ratio (ICR) to ensure your rent covers the mortgage payments. For HMOs, these stress rates are often higher than standard BTLs, frequently ranging between 160% and 170% to account for the increased management intensity.
- Property Standards: Your property must meet strict fire safety and building regulations. Lenders often require evidence of planning permission if you have converted a property from a standard C3 dwelling to a C4 HMO.
Strategic Considerations for Landlords
- Limited Company SPVs: Many landlords now use Special Purpose Vehicles (SPVs) to hold their HMO assets. This can offer tax efficiencies, though lenders will still assess the underlying property's viability and your experience as a landlord.
- Portfolio Assessment: If you are a portfolio landlord, lenders will look at your total debt exposure. Some may cap the number of properties or the total value of lending across their books, making it essential to diversify your lender panel.
- Deposit Requirements: While 25% is the industry standard, some specialist lenders may accept 20% for experienced landlords, while others might require 35% or more for complex, large-scale HMOs or properties in specific high-density areas.
Practical Guidance for Your Application
Before approaching a lender, ensure your financial documentation is impeccable. Lenders will want to see a clear business plan, especially for conversions, detailing how you intend to manage voids and maintenance costs. Remember that operating expenses for an HMO—including utilities, licensing fees, and management—can consume 25% to 33% of your gross rent.
Always stress-test your own model before committing to a purchase. Assume that a room may sit empty for several months, or that utility costs may rise. If your deal only remains profitable under perfect conditions, it is likely too risky for a specialist lender to support in the current 2026 market.
Next Steps
Navigating the specialist lending market requires more than just finding a product; it requires matching your specific property and business structure to the right lender's criteria. If you are planning an HMO purchase or looking to refinance an existing multi-let property, chat with Molly or speak to one of our specialist advisers today for a tailored assessment of your situation.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.