Joint Borrower Sole Proprietor: A 2026 Guide
Struggling to meet affordability criteria? Discover how a Joint Borrower Sole Proprietor (JBSP) mortgage can help you secure your home in 2026.
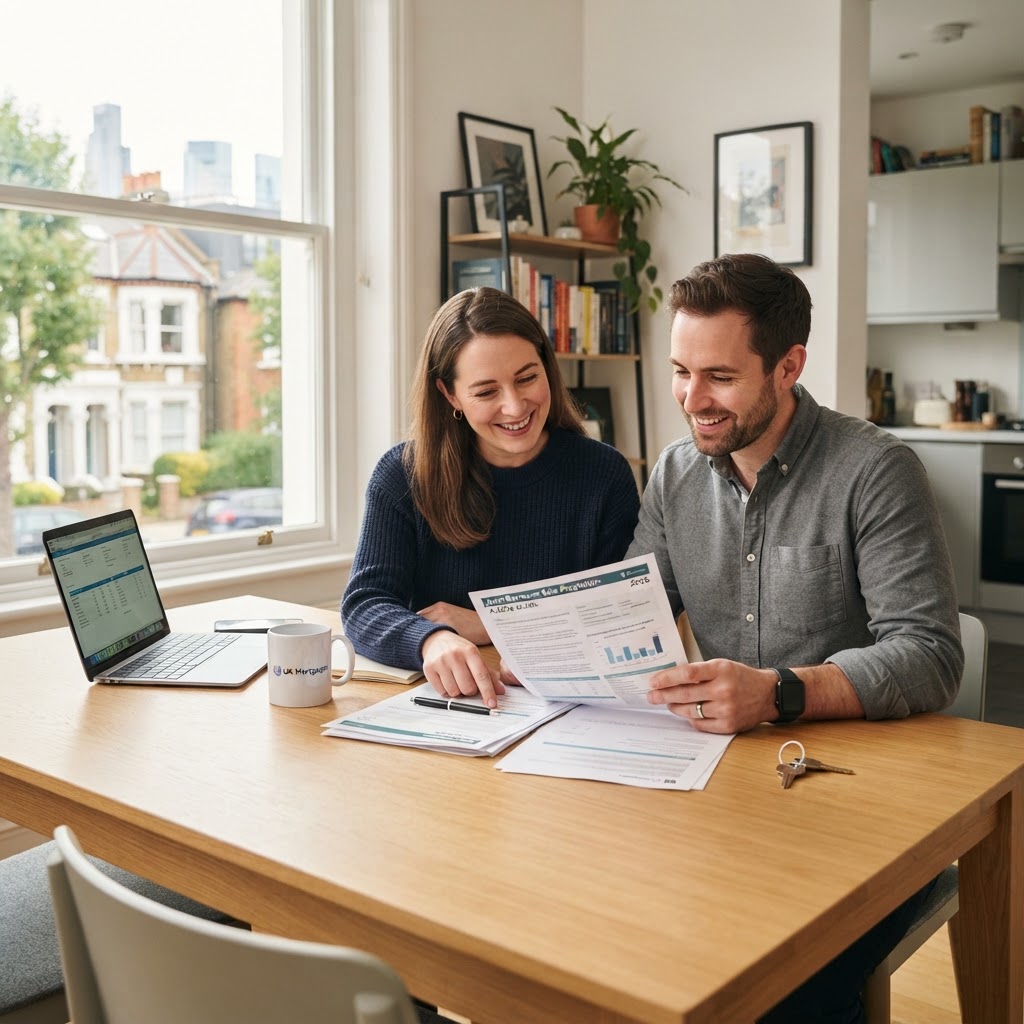
Joint Borrower Sole Proprietor: A 2026 Guide
Introduction: Boosting Your Borrowing Power
In the current economic climate, with the Bank of England base rate at 3.75% and inflation at 3.5%, many aspiring homeowners are finding it difficult to meet strict lender affordability criteria. If your individual income isn't quite enough to secure the mortgage you need, you might feel like the property ladder is slipping out of reach. A Joint Borrower Sole Proprietor (JBSP) mortgage offers a practical solution to bridge this gap.
This arrangement allows you to add a family member's income to your application to boost your borrowing power without them needing to be named on the property deeds. It is a powerful tool for those who have the deposit but lack the required income multiples to satisfy modern lending stress tests. This guide explores how this structure works and whether it is the right path for your home-buying journey.
What is a Joint Borrower Sole Proprietor Mortgage?
A JBSP mortgage is a specialized product where multiple people are responsible for the mortgage repayments, but only one person (or couple) is named on the property's title deeds as the legal owner. This is the fundamental difference between a JBSP and a standard joint mortgage. The "helper"—often a parent or family member—is legally liable for the debt but holds no ownership stake in the property.
Because the helper is not on the deeds, they do not face the same Stamp Duty implications as they would if they were buying a second home. This makes it a highly flexible way to get a first-time buyer into their own home. It effectively allows you to leverage the financial strength of your family to meet the lender's affordability requirements while you retain full control of the property asset.
How Affordability is Assessed in 2026
Lenders in 2026 are rigorous when assessing affordability, often using income multiples ranging from 4.5x to 7x depending on the lender and your specific financial profile. When you apply for a JBSP mortgage, the lender will look at the combined income of all borrowers to determine the maximum loan amount. They will also conduct a thorough review of all committed expenditure, including council tax, existing loans, and credit card commitments.
- Income Aggregation: By adding a family member's income, you can often access higher loan-to-income ratios that would otherwise be unavailable to you as a sole applicant.
- Stress Testing: Lenders will apply a stressed interest rate to ensure the mortgage remains affordable even if rates fluctuate. With the current base rate at 3.75%, lenders are cautious, so having a clear picture of your household outgoings is essential.
- Lender Criteria: Not all lenders offer JBSP products. It is vital to work with a broker who understands which lenders are currently active in this space and which ones offer the most competitive rates for your specific circumstances.
Practical Considerations for Borrowers
Before proceeding with a JBSP arrangement, it is important to have open conversations with your family members. Since they are legally responsible for the mortgage, they must be fully aware of the risks involved. If you are unable to make the monthly repayments, the lender will look to the other borrowers to cover the shortfall, which could impact their own credit files and financial stability.
It is also advisable to seek independent legal advice to ensure that all parties understand their rights and responsibilities. While the helper does not own the property, they are still on the hook for the debt. Many families choose to put a private agreement in place to outline how the arrangement will work and what happens if the borrower's circumstances change, such as a change in employment or a desire to remortgage in the future.
Next Steps
Navigating the complexities of JBSP mortgages requires expert guidance to ensure you choose the right lender and structure for your needs. Whether you are looking to boost your borrowing power or need help understanding how your income fits into current market criteria, we are here to help. Chat with Molly or speak to one of our expert advisers today for personalized advice tailored to your unique situation.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.