Later-Life Lending: Securing a Mortgage Into Retirement
Navigating later-life lending in 2026. Learn how to secure a mortgage into retirement using pension income and sustainable long-term affordability strategies.
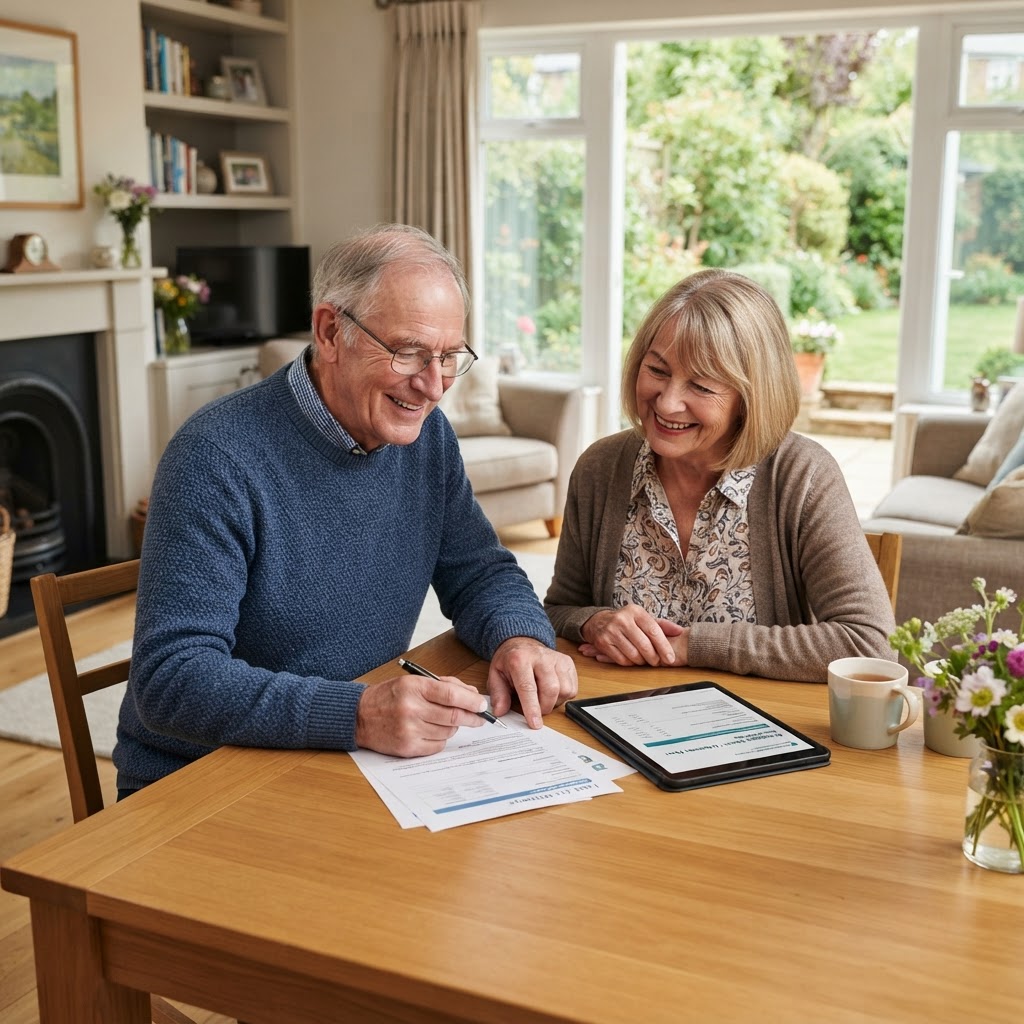
Later-Life Lending: Securing a Mortgage Into Retirement
Introduction: Planning for Your Future Home
Many borrowers today are looking to extend their mortgage terms well into their retirement years. Whether you are looking to downsize, move closer to family, or simply remain in your current home, the lending landscape has evolved to accommodate these needs. Understanding how lenders assess your income beyond your working life is the first step toward securing your financial future.
In 2026, the mortgage market is increasingly flexible, but it requires a clear strategy regarding how you will fund your repayments. With the Bank of England base rate at 4.00% and inflation at 3.5%, lenders are focused on long-term sustainability. This guide explores how you can navigate the criteria for lending into retirement effectively.
Understanding Lending Into Retirement
Lending into retirement is no longer a niche product; it is a standard feature across many residential and buy-to-let ranges. Lenders generally define retirement age as either your stated retirement date or age 70, whichever comes first. If your mortgage term extends beyond this point, you must demonstrate how you will maintain payments without relying on active employment income.
Affordability is typically assessed using the lower of your current income or your projected retirement income. This includes private pensions, state pensions, annuities, and income from sustainable investments. Because lenders need to be certain that your income is sustainable for the life of the loan, they will often request detailed pension statements or letters from scheme administrators to verify your future cash flow.
Key Considerations for Your Application
- Income Verification: You must provide evidence of your pension pot or projected income. Lenders often use the central growth estimate from your latest pension statement, typically dated within the last 12 months.
- Retirement Interest-Only (RIO) Mortgages: These products allow you to pay only the interest each month, with the capital repaid when the property is eventually sold. This can be an excellent solution for those who have significant equity but limited monthly income.
- Joint Applications: If you are applying with a partner, lenders will often assess affordability based on the lowest earner to ensure that a surviving borrower can maintain the mortgage payments independently.
- Age Limits: While some lenders have a maximum age at the end of the term (often 80), others are more flexible if you can provide robust evidence of your retirement income strategy.
Practical Guidance for Borrowers
When preparing your application, transparency is your greatest asset. Start by gathering your most recent pension statements and any documentation regarding other income sources, such as rental income or investment dividends. If you are still working, ensure your current income is well-documented, as this will be used alongside your retirement projections to stress-test your affordability.
It is also vital to consider the type of mortgage that suits your long-term goals. If you intend to stay in the property for the rest of your life, a RIO mortgage might be more appropriate than a standard repayment mortgage. Conversely, if you plan to pay off the capital, you will need a clear repayment strategy that satisfies the lender's strict criteria regarding sustainable income.
Next Steps
Navigating the complexities of later-life lending requires a tailored approach that aligns with your specific pension and investment profile. If you are unsure how your income will be viewed by lenders or want to explore your options for lending into retirement, we are here to help. Chat with Molly or speak to one of our specialist advisers today to discuss your circumstances and secure a mortgage that works for your future.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.