Lending Into Retirement: Your Options in 2026
Approaching retirement but need a mortgage? Discover how to navigate lending into retirement, RIO mortgages, and affordability checks in the current 2026 market.
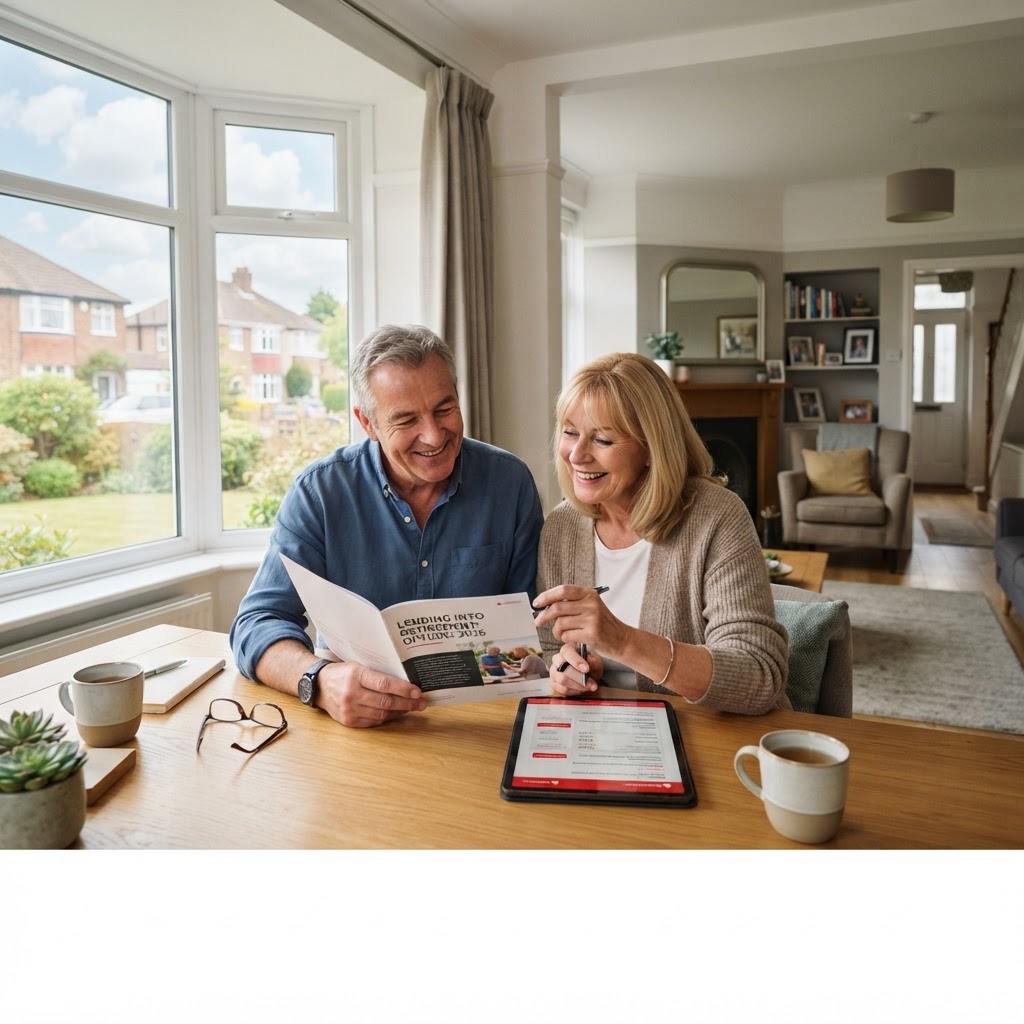
Lending Into Retirement: Your Options in 2026
Introduction: Planning Your Mortgage Beyond Retirement
Many borrowers assume that reaching a certain age automatically closes the door on mortgage options. In reality, the 2026 lending landscape is increasingly flexible for those planning to work longer or transition into retirement while maintaining a mortgage. Whether you are looking to remortgage your family home or purchase a new property, understanding how lenders view your income is the first step.
With the Bank of England base rate currently at 3.75% and inflation at 3.5%, lenders are scrutinising affordability more closely than ever. This article explores how you can secure lending into retirement and the specific criteria you need to meet to satisfy modern underwriting standards. We will look at how your pension, investments, and future earnings are assessed to ensure your long-term financial security.
Understanding 'Lending Into Retirement'
'Lending into retirement' refers to any mortgage term that extends beyond your intended retirement age. Lenders have become more sophisticated in how they assess these applications, moving away from rigid age caps toward a more nuanced view of your total financial picture. Most lenders will now require you to provide clear evidence of your projected retirement income, such as pension statements or private investment drawdown plans.
When you are within 10 years of retirement, many lenders will assess your affordability based on the lower of your current earned income or your estimated future pension income. This is a critical distinction that can significantly impact your maximum borrowing capacity. It is essential to prepare your documentation early, as lenders will want to see a clear, sustainable plan for how the mortgage will be serviced once your primary salary ceases.
Key Mortgage Structures for Later Life
- Standard Residential Mortgages: Many high-street lenders now allow terms that extend into your 70s or 80s, provided you can prove your pension income is sufficient to cover the monthly payments. You must demonstrate that your retirement income meets the lender's specific stress-test requirements.
- Retirement Interest-Only (RIO) Mortgages: These are designed specifically for older borrowers who wish to pay only the interest each month. Unlike standard mortgages, RIOs often have no maximum age at the end of the term, making them a popular choice for those looking to manage monthly outgoings without the pressure of capital repayment.
- Asset-Based Lending: For high-net-worth individuals with substantial investments but limited pension income, some specialist lenders focus on your overall balance sheet. They may assess your property equity, investment portfolios, and liquid assets rather than relying solely on traditional payslips.
Practical Guidance for Your Application
Before approaching a lender, it is vital to conduct a thorough review of your financial outgoings. Lenders will deduct all personal expenditure, including existing loans and credit card balances, from your affordability calculation. If you have debts that will be cleared upon completion of the mortgage, ensure you have evidence of this, as it can improve your borrowing power.
Consider the impact of your chosen retirement age on your mortgage term. If you plan to retire at 65, but your mortgage term extends to 75, you must be prepared to provide detailed pension projections. Working with a specialist broker can help you navigate the varying criteria across different building societies and private banks, ensuring you choose a product that aligns with your long-term retirement strategy.
Next Steps
Navigating the complexities of later-life lending requires a tailored approach that considers your unique income streams and future goals. If you are concerned about how your retirement plans might affect your mortgage eligibility, chat with Molly or speak to one of our expert advisers today for a personalised assessment of your situation.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.