Navigating Life-Stage Lending: Mortgages for Every Chapter
Discover how to manage your mortgage needs during major life transitions. From upsizing to retirement, learn how to adapt your home finance strategy in 2026.
Navigating Life-Stage Lending: Mortgages for Every Chapter
Introduction: Adapting Your Mortgage to Life's Changes
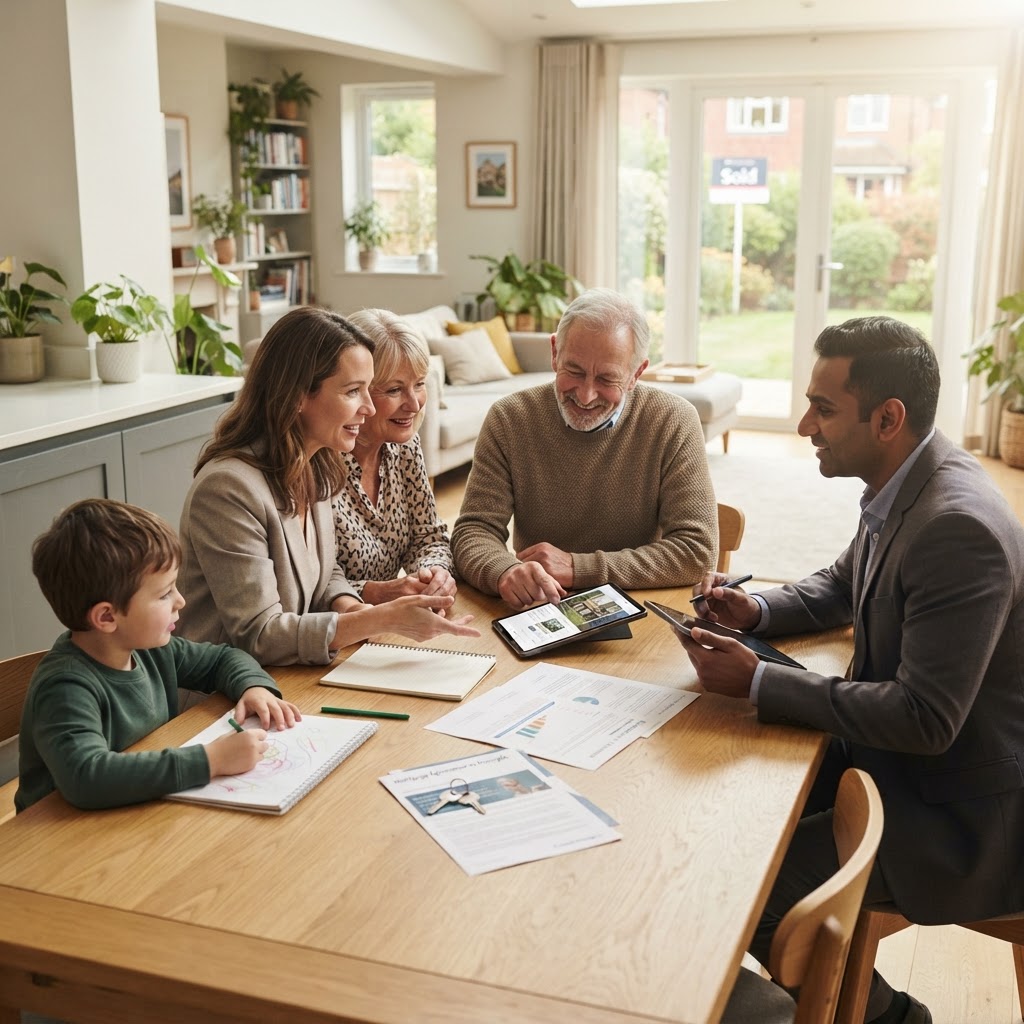
Life is rarely static, and your mortgage needs will likely evolve as you move through different chapters. Whether you are upsizing for a growing family, navigating a divorce, or planning for a comfortable retirement, your home finance strategy requires careful adjustment. Understanding how lenders view these transitions is essential for maintaining financial stability in the current economic climate.
As of October 2026, the UK mortgage market remains sensitive to broader economic factors, with the Bank of England base rate holding at 3.75% and CPI inflation at 3.1%. These figures influence how lenders assess affordability and risk across various life stages. This guide explores how to approach your mortgage during significant life events while keeping your long-term goals in focus.
Upsizing and Growing Families
When your family grows, the need for more space often becomes a priority. Upsizing typically involves moving from a smaller property to a larger one, which often requires a larger loan amount and a reassessment of your current equity. With average 5-year fixed rates currently hovering around 5.51%, it is vital to calculate your new monthly repayments accurately before committing to a larger mortgage.
Managing the Transition
- Equity Assessment: Use the equity built up in your current home to secure a better Loan-to-Value (LTV) ratio on your next property. Lower LTV bands, such as 60% or 75%, often unlock more competitive interest rates.
- Affordability Checks: Lenders will conduct rigorous stress tests to ensure you can afford the higher repayments. Ensure your household budget accounts for the current 3.1% inflation environment and potential future rate fluctuations.
Mortgages During Divorce or Separation
Separation is a challenging time, and untangling joint finances is a critical step in the process. Often, one partner may wish to remain in the family home, which requires a process known as a 'transfer of equity' or a remortgage to remove one party from the existing loan. This requires the remaining borrower to prove they can sustain the mortgage payments independently.
- Financial Disclosure: Be prepared to provide full transparency regarding income, debts, and assets to your lender.
- Legal Advice: Always coordinate with a solicitor to ensure the property title and mortgage liability are updated correctly to avoid future complications.
Later-Life Lending and Retirement
Retirement planning is no longer just about pensions; it is about managing your property wealth effectively. Many borrowers now look for flexibility in their later years, whether through downsizing or specialist products like Retirement Interest-Only (RIO) mortgages. These products allow you to pay only the interest on your loan, with the capital repaid when the property is sold or upon death or long-term care entry.
Key Considerations for Retirees
- Income Verification: Lenders will focus on your retirement income, including private pensions and investments, to ensure long-term affordability.
- Downsizing Strategy: If you plan to move to a smaller, more manageable home, consider the costs of moving versus the potential to release equity for your retirement fund.
Practical Guidance for Every Stage
Regardless of your life stage, preparation is the most effective tool in your arsenal. Start by reviewing your current mortgage deal and checking if you are within your fixed-rate period, as early repayment charges can significantly impact your budget. Always maintain a buffer in your savings to account for the current economic volatility and the impact of the 3.75% base rate on variable-rate products.
Next Steps
Navigating life-stage lending can be complex, but you do not have to do it alone. Whether you are upsizing, separating, or planning for retirement, our team is here to help you find the right path. Chat with Molly or speak to one of our expert advisers today for personalized guidance tailored to your unique circumstances.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.