Protecting Your Home: A 2026 Guide to Mortgage Insurance
Is your home protected? Discover the essential types of mortgage insurance in 2026 to ensure your family stays secure if the unexpected happens.
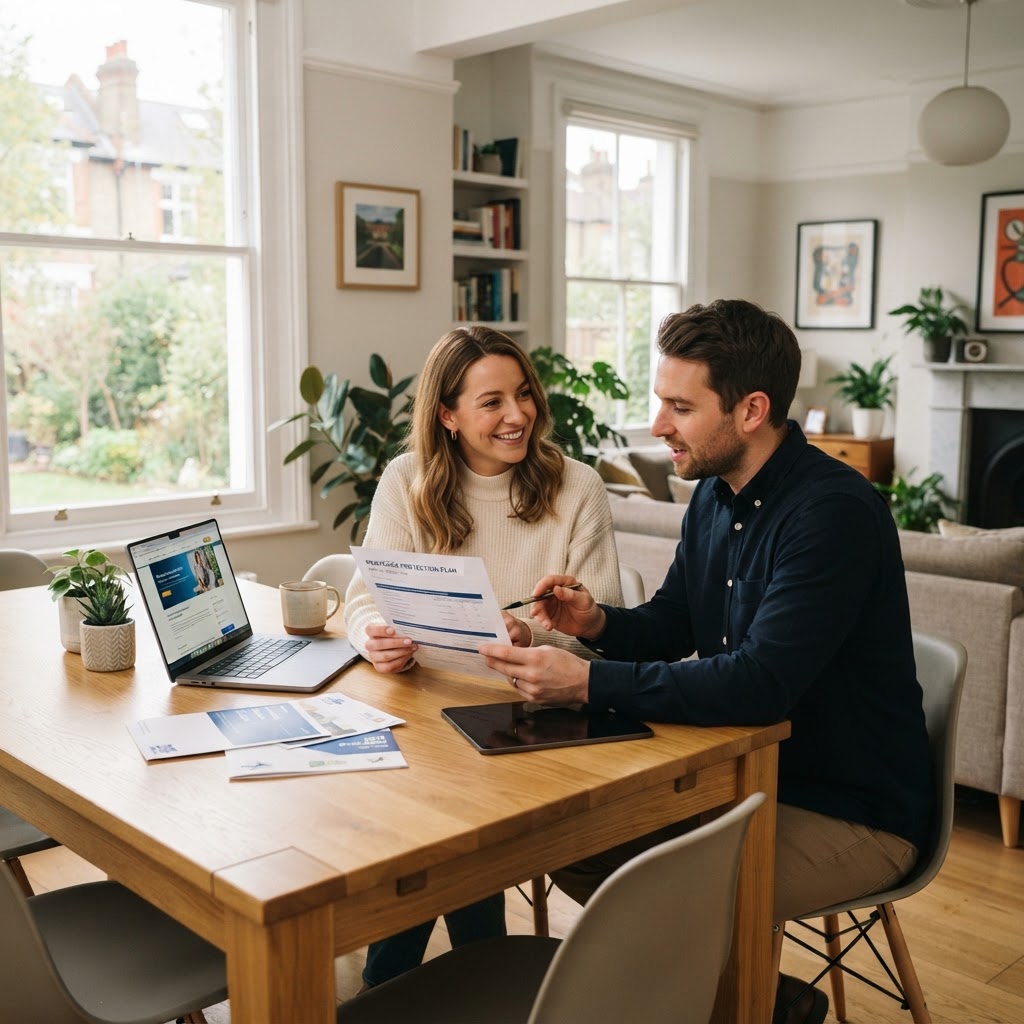
Protecting Your Home: A 2026 Guide to Mortgage Insurance
Introduction: Why Protection Matters Your mortgage is likely the largest financial commitment you will ever make. While securing the loan is a major milestone, ensuring that you can maintain those payments regardless of life's uncertainties is equally vital. In 2026, with many households managing tight budgets, having a robust protection plan is no longer optional—it is a necessity for long-term peace of mind. This guide explores the different types of insurance available to help you safeguard your property and your loved ones. We will break down the differences between life insurance, critical illness cover, and income protection to help you make an informed decision.
Understanding Mortgage Protection Insurance Mortgage protection insurance, often referred to as decreasing term life insurance, is specifically designed to pay off your mortgage balance if you pass away during the policy term. Because the cover amount decreases in line with your mortgage balance, it is often a more cost-effective way to ensure your home is mortgage-free for your family. It provides a targeted safety net that is directly linked to your property debt.
Why Standard Life Insurance Might Be Better While mortgage protection is specific, many homeowners opt for level term life insurance instead. With standard life insurance, the payout remains fixed throughout the term, which can provide extra funds for your family to cover living costs beyond just the mortgage. This flexibility makes it a popular choice for those who want to ensure their dependents are fully supported.
Key Types of Protection to Consider
Critical Illness Cover: This policy pays out a tax-free lump sum if you are diagnosed with a specific serious illness, such as cancer, a heart attack, or a stroke. It can help you pay off your mortgage or cover medical expenses during a difficult recovery period.
Income Protection: If you are unable to work due to illness or injury, this insurance provides a monthly tax-free income. It is designed to cover your essential outgoings, including your mortgage payments, until you are fit to return to work or reach retirement.
Buildings and Contents Insurance: While life-related policies protect you, buildings insurance is a mandatory requirement for almost all mortgage lenders. It covers the physical structure of your home against risks like fire, flood, or storm damage.
Practical Guidance for Homeowners Research from the Association of Mortgage Intermediaries indicates that a significant portion of UK mortgage holders currently lack any form of protection. This leaves families vulnerable to financial hardship if a primary earner can no longer contribute. Do not wait until a health scare or life event forces you to consider your options. Start by reviewing your current monthly outgoings and identifying the "gap" that would exist if your income were to stop. Even a basic policy can provide a vital buffer, and premiums can start from as little as £5 per month depending on your age and health profile.
Next Steps Protecting your home is a crucial step in your property journey. If you are unsure which type of cover is right for your specific circumstances, our team is here to help. Chat with Molly or speak to one of our expert advisers today for personalized guidance on securing your family's future. --
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.