Self-Employed Mortgages: A 2026 Guide for UK Borrowers
Navigating the mortgage market as a self-employed professional? Discover how to secure a home loan in 2026 with our expert guide on income proof and lenders.
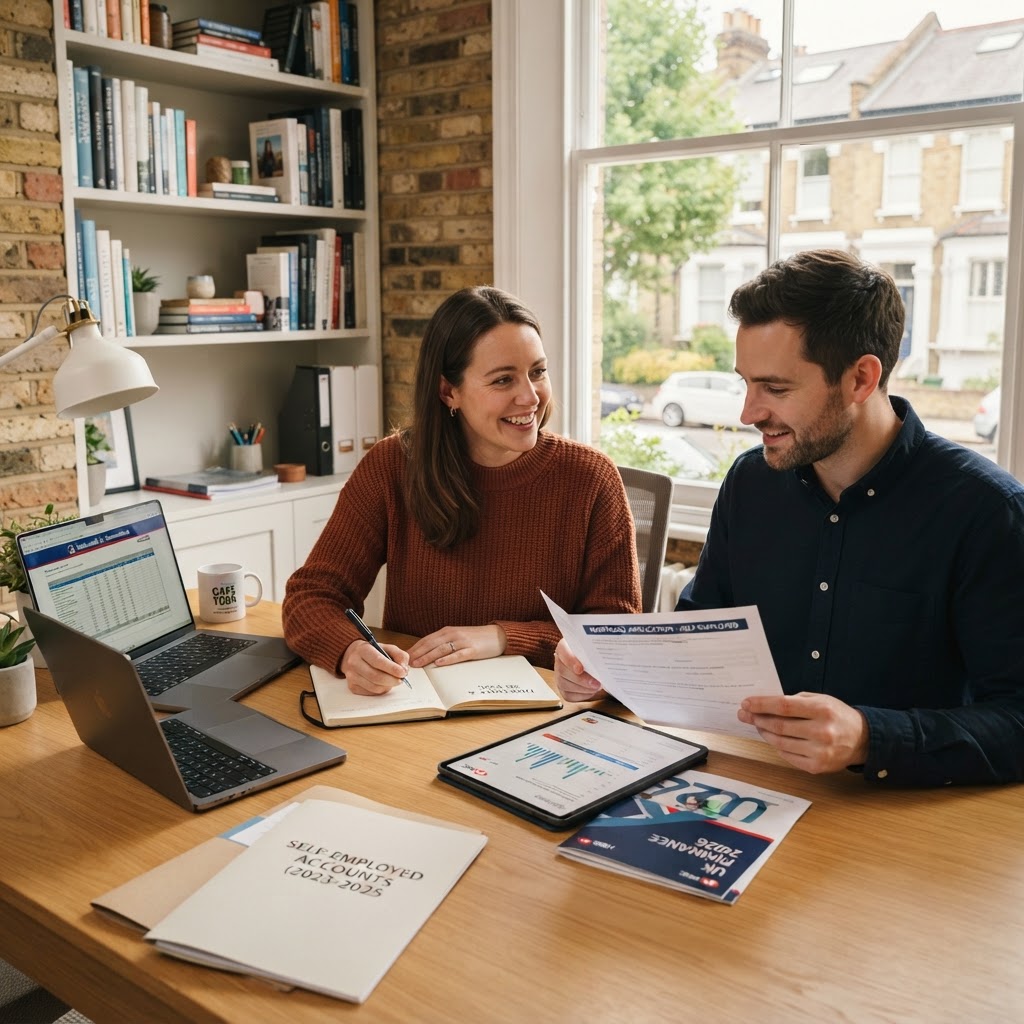
Self-Employed Mortgages: A 2026 Guide for UK Borrowers
Introduction: Securing a Mortgage When You Work for Yourself
Being self-employed should never be an obstacle to achieving your homeownership dreams. While the application process can feel more rigorous than for those in traditional employment, many lenders are well-equipped to handle non-standard income structures. With the Bank of England base rate currently at 3.75% and inflation at 3.1%, understanding how to present your financial health is key to securing a competitive deal.
This guide explores the essential requirements for self-employed applicants in the current 2026 market. We will cover the documentation you need, how lenders assess your income, and practical steps to improve your chances of approval. Whether you are a sole trader, contractor, or company director, preparation is your greatest asset.
Understanding Lender Requirements
Most high-street lenders typically require at least two years of trading history to verify your income stability. While some specialist lenders may consider applications with only one year of accounts, having a longer, consistent track record significantly strengthens your position. Lenders generally define you as self-employed if you own more than 20% to 25% of a business from which you derive your primary income.
Essential Documentation
To prove your affordability, you must be prepared to provide comprehensive financial evidence. Lenders will typically request:
- Certified Accounts: Ideally prepared by a qualified accountant, covering at least two years of trading.
- Tax Documents: Your SA302 forms or tax year overviews from HMRC are standard requirements.
- Bank Statements: Recent personal and business bank statements to demonstrate consistent cash flow and expenditure.
- Business Contracts: If you are a contractor, providing evidence of ongoing or future work can help demonstrate long-term income security.
How Lenders Evaluate Your Income
Lenders do not just look at your total revenue; they focus on your net profit or the salary and dividends you draw from your business. It is vital to ensure your accounts are up to date and accurately reflect your earnings, as this is the primary figure used for your mortgage affordability stress test.
- Income Consistency: Lenders look for a stable or upward trend in your earnings over the last two to three years.
- Business Structure: Whether you operate as a sole trader or a limited company can influence which lenders are the best fit for your specific circumstances.
- Joint Applications: If you are applying with a partner who is traditionally employed, their income can help balance the application, though lenders will still scrutinise the self-employed portion of your household income.
Practical Steps for Success
Before you start house hunting, take the time to organise your financial house. Ensure your business accounts are filed on time and that your tax returns are fully up to date. If you have recently changed your business structure, such as moving from a sole trader to a limited company, speak to an adviser early, as this can impact how lenders calculate your borrowing capacity.
Consider the current market environment where average 2-year fixed rates at 60% LTV are around 5.13%. By maintaining a clean credit file and having a clear, documented history of your income, you can position yourself to access the best available rates. Remember that specialist lenders often have more flexible criteria for those with complex income streams, which is why professional guidance is invaluable.
Next Steps
Navigating the mortgage market as a self-employed borrower requires a tailored approach. If you are ready to explore your options or need help preparing your application, chat with Molly today or speak to one of our expert advisers for personalized, professional guidance.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.