Understanding Mortgage Conveyancing: A 2026 Guide
Demystifying the legal process of buying a home. Learn what conveyancing involves, how long it takes, and how to manage costs in the current 2026 UK market.
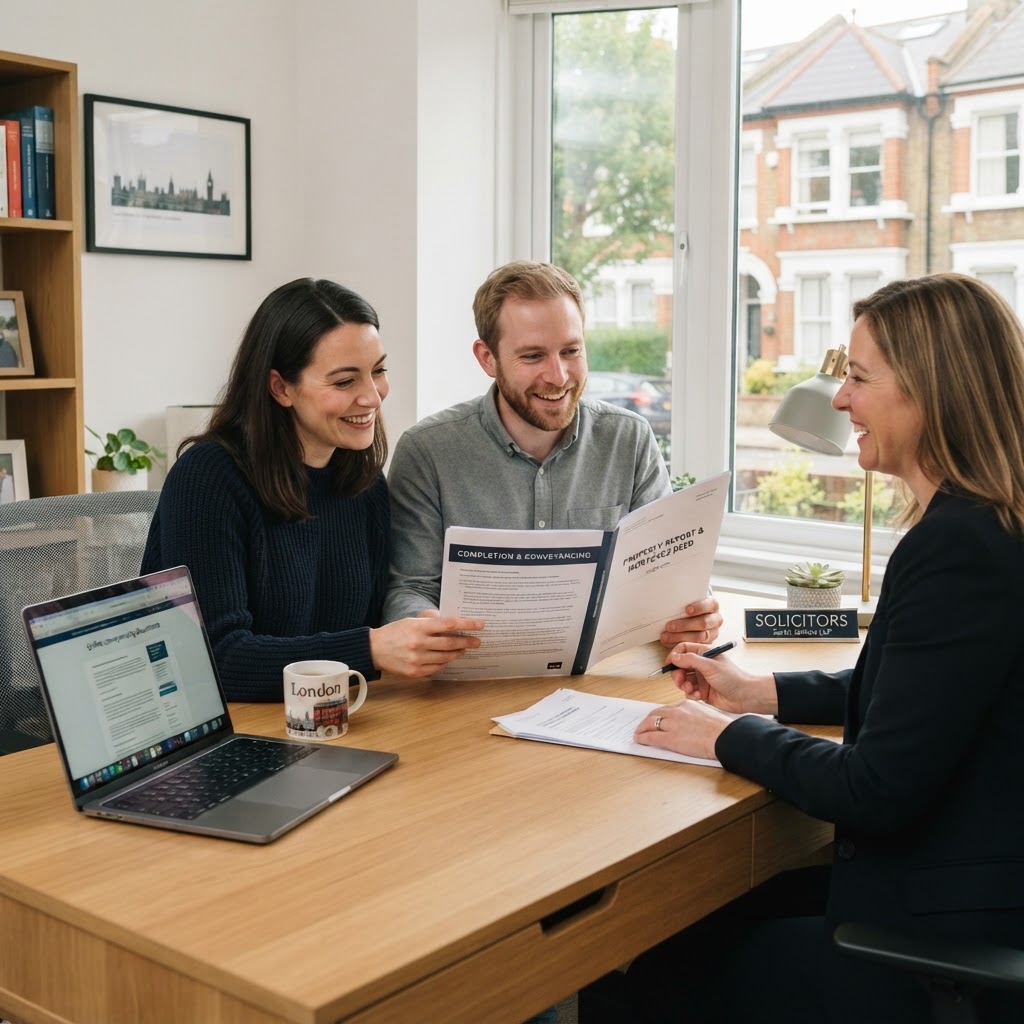
Understanding Mortgage Conveyancing: A 2026 Guide
Introduction: Navigating the Legal Maze
Securing a mortgage offer is a major milestone, but it is only half the battle when purchasing a property. Once your offer is accepted, you enter the world of conveyancing, the legal process of transferring property ownership from the seller to you. For many buyers, this stage can feel like a complex, jargon-filled hurdle that slows down the excitement of moving into a new home.
In the current 2026 market, where the Bank of England base rate sits at 3.75% and inflation remains a factor at 2.8%, efficiency is key to protecting your financial position. Understanding the steps involved can help you avoid unnecessary delays and keep your transaction on track. This guide breaks down exactly what your conveyancer does and how you can support the process.
What is Conveyancing and Why Do You Need It?
Conveyancing is the legal transfer of property title from one person to another. Because property law in the UK is intricate, you are legally required to appoint a licensed conveyancer or solicitor to handle the transaction. They act as the bridge between you, the seller, the estate agent, and your mortgage lender.
Your conveyancer is responsible for ensuring that the property you are buying is legally sound. They conduct essential searches, check the title deeds, and handle the exchange of contracts. Without this professional oversight, you could be left with significant legal liabilities or issues that could impact your ability to sell the property in the future.
The Core Stages of the Conveyancing Process
- Instruction and Initial Checks: Once you instruct a solicitor, they will verify your identity and request your initial deposit for searches. They will also contact the seller’s solicitor to request the draft contract and supporting documents.
- Property Searches: Your solicitor will perform local authority, environmental, and drainage searches. These reveal vital information, such as planned developments nearby or potential flood risks, which are crucial in today’s climate-conscious market.
- Raising Enquiries: Based on the search results and the contract, your solicitor will raise specific questions for the seller. This is a critical stage where any discrepancies in the property’s history or boundaries are addressed.
- Mortgage Offer Review: Your solicitor will review your formal mortgage offer from your lender to ensure all conditions are met. They must confirm that the lender’s requirements are satisfied before you can proceed to exchange.
- Exchange and Completion: Once all parties are satisfied, contracts are signed and exchanged, making the sale legally binding. Completion follows, usually a few weeks later, when the funds are transferred and you receive the keys to your new home.
Managing Costs and Timelines in 2026
Conveyancing fees can vary significantly depending on the complexity of the transaction and the value of the property. On average, you should budget between £1,000 and £2,500 for legal fees and disbursements, such as search fees and Land Registry charges. Always ask for a transparent, itemised quote upfront to avoid hidden costs later in the process.
Timelines are currently influenced by the volume of transactions and the responsiveness of local authorities. While a straightforward purchase might take 12 to 16 weeks, complications can extend this. Staying proactive by returning documents promptly and keeping in regular contact with your solicitor can help shave valuable time off the process.
Practical Guidance for a Smoother Move
Communication is the most effective tool you have during the conveyancing process. Respond to your solicitor’s requests for information immediately, as even a one-day delay can cause a chain reaction that pushes back your completion date. If you are part of a property chain, ensure your solicitor is aware of the needs of other parties involved.
Additionally, ensure your finances are ready well in advance. Your solicitor will need proof of your deposit funds, and any delays in verifying the source of these funds can stall the entire transaction. By being organised and prepared, you can navigate the legal requirements with confidence and focus on the excitement of your move.
Next Steps
Navigating the legal side of a property purchase is much easier when you have the right team behind you. If you have questions about how the conveyancing process fits into your specific mortgage journey, or if you need advice on managing your property budget, we are here to help. Chat with Molly or speak to one of our expert advisers today for personalized guidance tailored to your circumstances.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.