Understanding Mortgage Stress Tests in 2026
Navigating mortgage affordability in 2026. Learn how lenders calculate stress tests with a 3.75% base rate and what it means for your borrowing power.
Understanding Mortgage Stress Tests in 2026
Introduction: Why Affordability Matters Now
In the current economic climate, securing a mortgage involves more than just meeting a minimum deposit requirement. With the Bank of England base rate at 3.75% and inflation at 3.1%, lenders are applying rigorous stress tests to ensure borrowers can handle potential future rate fluctuations. Understanding these calculations is essential for anyone looking to purchase a home or remortgage in the current market.
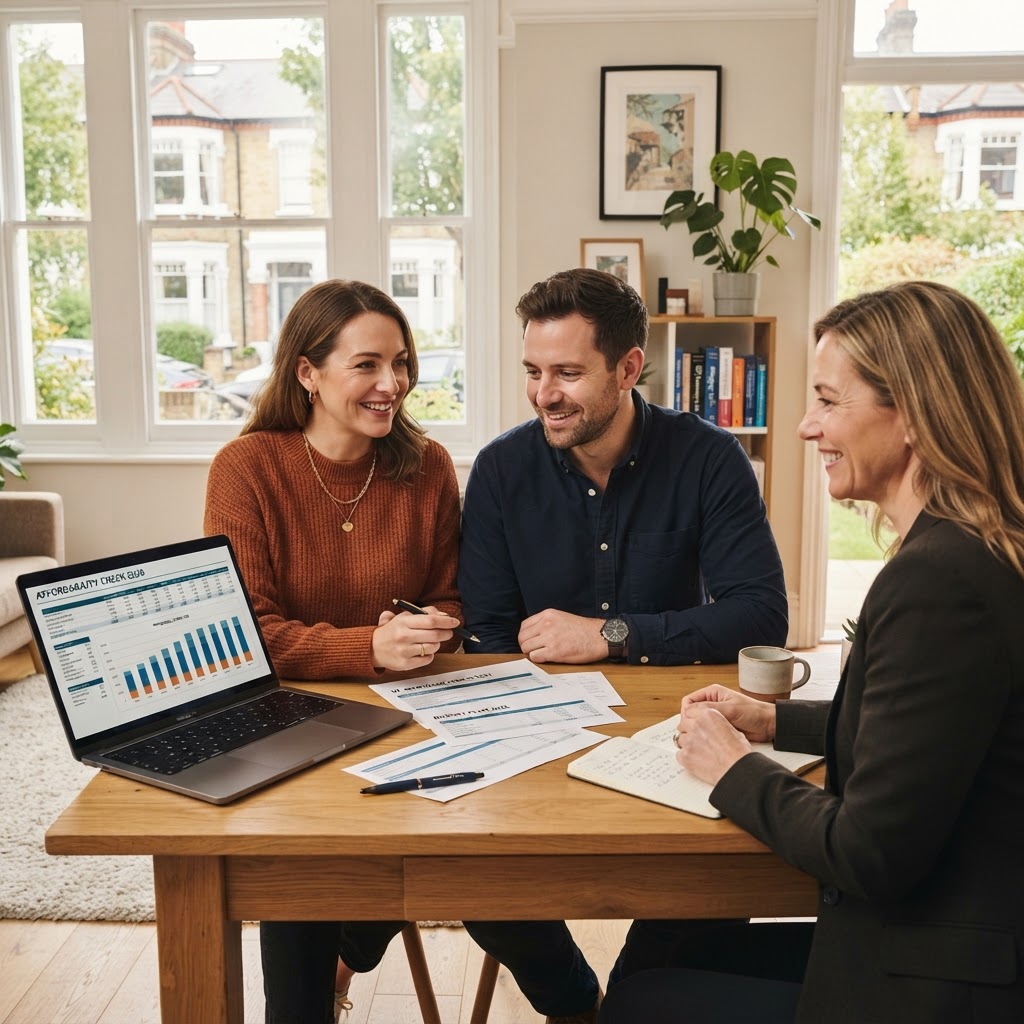
These stress tests are designed to protect both the lender and the borrower from financial hardship. By simulating higher interest rates, banks assess whether your household budget can withstand economic shifts. This article breaks down how these tests work and how they impact your total borrowing capacity in 2026.
How Lenders Calculate Your Affordability
When you apply for a mortgage, lenders do not just look at the current interest rate you are offered. They apply a 'stress rate'—a hypothetical interest rate significantly higher than your actual product rate—to see if you could still afford the monthly repayments. This ensures that if rates rise further, you are not left in a position where you cannot meet your obligations.
For example, if you are applying for a mortgage with a product rate of 5.00%, a lender might stress test your income against a rate of 7.50% or higher. This calculation is performed alongside a thorough review of your committed expenditure, including credit card debts, personal loans, and essential living costs. Even with a strong salary, high levels of existing debt can significantly reduce the amount a lender is willing to offer you.
The Impact of the 3.75% Base Rate
With the base rate currently at 3.75%, the cost of borrowing has remained elevated compared to previous years. Lenders are particularly cautious, often requiring a higher 'interest coverage ratio' for certain types of lending. This means that your net monthly income must comfortably exceed your projected mortgage payments by a specific margin, providing a buffer against inflation and rising costs.
Key Factors Influencing Your Borrowing Power
- Committed Expenditure: Lenders subtract your monthly debt repayments from your income before calculating your mortgage capacity. Reducing personal loans or clearing credit card balances before applying can improve your results.
- Loan-to-Value (LTV) Ratios: A larger deposit often grants you access to lower interest rates, which in turn makes it easier to pass the stress test. Borrowers with a 60% LTV often face less stringent affordability hurdles than those with a 90% LTV.
- Income Stability: For the self-employed or those with variable income, lenders may use a more conservative average of your earnings. Providing clear, consistent financial records is vital to demonstrating your ability to maintain payments.
- Future-Proofing: Lenders consider your age and the length of the mortgage term. A longer term reduces monthly payments but increases the total interest paid, which is a factor in their long-term risk assessment.
Practical Guidance for Prospective Borrowers
Before you start house hunting, it is wise to conduct your own 'stress test' on your finances. Calculate your monthly budget using a rate 2-3% higher than the current market average to see if you would still feel comfortable. This proactive approach helps you avoid disappointment when a lender’s formal assessment comes back lower than you expected.
Additionally, ensure your credit file is in the best possible shape. Small errors or missed payments can trigger a more cautious approach from underwriters, especially when the market is as sensitive as it is in late 2026. Being transparent about your financial situation from the outset allows your adviser to match you with the most suitable lender for your specific profile.
Next Steps
Navigating the complexities of mortgage affordability can be challenging, but you don't have to do it alone. If you are concerned about how current stress tests might affect your borrowing power, chat with Molly or speak to one of our expert advisers today. We can provide a personalized assessment of your situation and help you find the right path to your next home.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.