Understanding Property Surveys: A 2026 Homebuyer's Guide
Don't skip the survey. Learn why a property survey is essential for protecting your investment in the 2026 UK housing market and how it differs from a valuation.
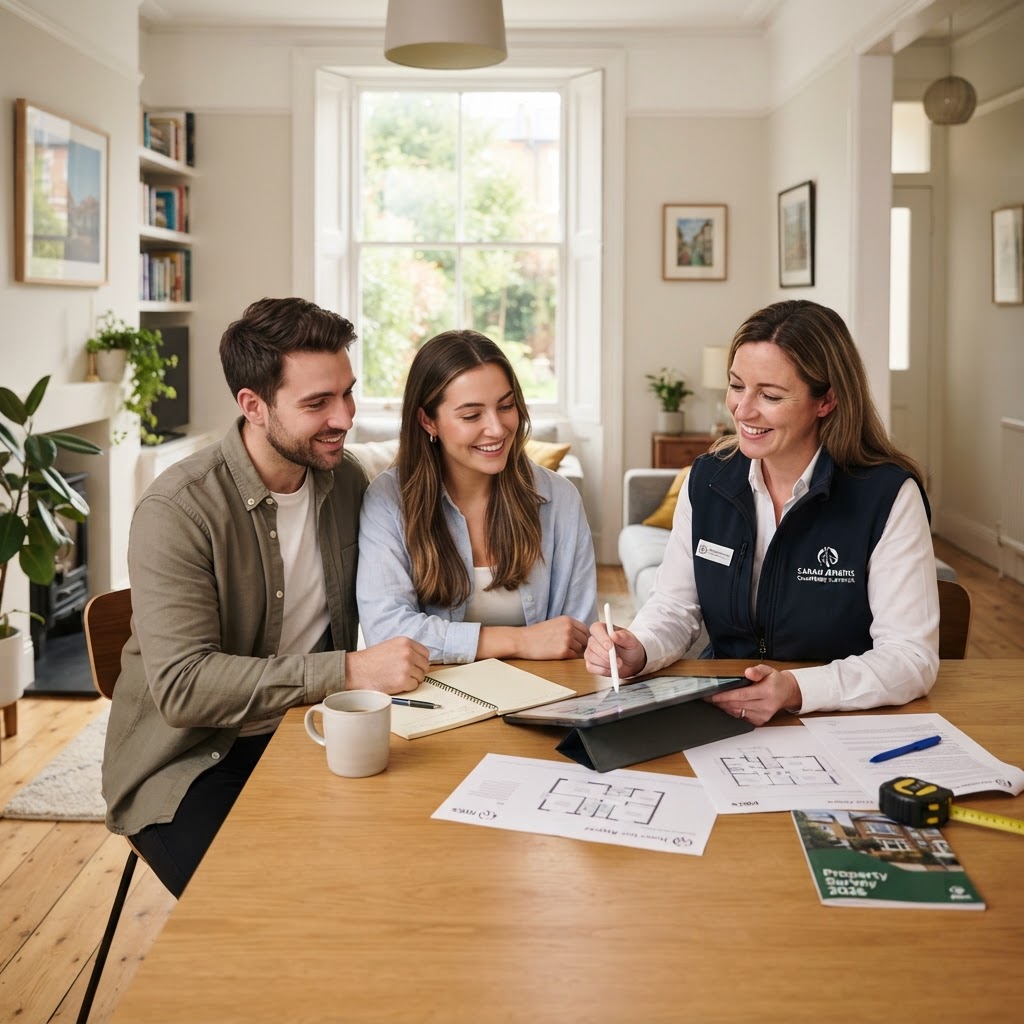
Understanding Property Surveys: A 2026 Homebuyer's Guide
Introduction: Why Your Mortgage Valuation Isn't Enough
When you are in the process of buying a home, it is easy to get caught up in the excitement of mortgage offers and conveyancing. Many buyers mistakenly believe that the mortgage valuation conducted by their lender provides a comprehensive check on the property's condition. In reality, a lender's valuation is strictly for the bank's benefit to ensure the property is worth the loan amount, and it offers no protection to you as the buyer.
In the current 2026 market, where buyer demand has softened due to interest rate expectations and economic uncertainty, protecting your investment is more critical than ever. With the Bank of England base rate holding at 3.75% and inflation at 3.5%, every pound of your budget counts. Commissioning an independent property survey is the only way to uncover hidden defects that could cost you thousands in repairs later.
This guide explores the different types of surveys available and why they are a non-negotiable step in your home-buying journey. Whether you are purchasing a period property or a modern build, understanding the physical state of your future home is essential for peace of mind.
The Difference Between Valuations and Surveys
It is a common misconception that a mortgage valuation is a survey. A mortgage valuation is a brief assessment performed by the lender to confirm the property provides adequate security for the mortgage. It does not look for structural issues, damp, or electrical faults, and the report is often not even shared with the buyer.
An independent survey, by contrast, is commissioned by you and performed by a qualified surveyor. The surveyor acts on your behalf to provide a detailed report on the property's condition. This report can be a powerful tool during negotiations; if significant issues are found, you may be able to renegotiate your offer or ask the seller to complete repairs before exchange.
Types of Surveys Available in 2026
Choosing the right survey depends on the age, size, and condition of the property you are buying. Here are the most common options:
- RICS Home Survey Level 1 (Condition Report): This is the most basic level of survey. It provides a 'traffic light' rating system to highlight any urgent defects but does not go into significant detail. It is generally best suited for modern, standard-construction homes in good condition.
- RICS Home Survey Level 2 (HomeBuyer Report): This is the most popular choice for the majority of homebuyers. It includes a detailed inspection of the property's condition, including accessible areas like the roof space and cellar. It also provides advice on maintenance and potential risks to the property.
- RICS Home Survey Level 3 (Building Survey): Formerly known as a full structural survey, this is the most comprehensive option. It is highly recommended for older properties, listed buildings, or homes that have undergone significant renovations. It provides an in-depth analysis of the property's construction and identifies potential long-term repair costs.
Practical Guidance for Homebuyers
When you are ready to book your survey, timing is everything. It is best to arrange your survey as soon as your offer is accepted and your mortgage application is underway. This ensures that if any major issues are discovered, you have time to address them before you are legally committed to the purchase.
Remember that a survey is an investment in your future. While it may feel like an additional cost during an expensive moving process, the cost of a survey is negligible compared to the potential expense of fixing a major structural issue after you have moved in. Always ensure your surveyor is registered with the Royal Institution of Chartered Surveyors (RICS) to guarantee they adhere to professional standards.
Next Steps
Navigating the property market in 2026 requires careful planning and expert support. If you are unsure which survey is right for your property or need help managing your overall moving costs, we are here to help. Chat with Molly or speak to one of our expert advisers today for personalized guidance tailored to your specific circumstances.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.