Understanding Stamp Duty: A 2026 Homebuyer's Guide
Navigating Stamp Duty Land Tax in 2026? Learn how current thresholds, first-time buyer reliefs, and property costs impact your home-buying budget.
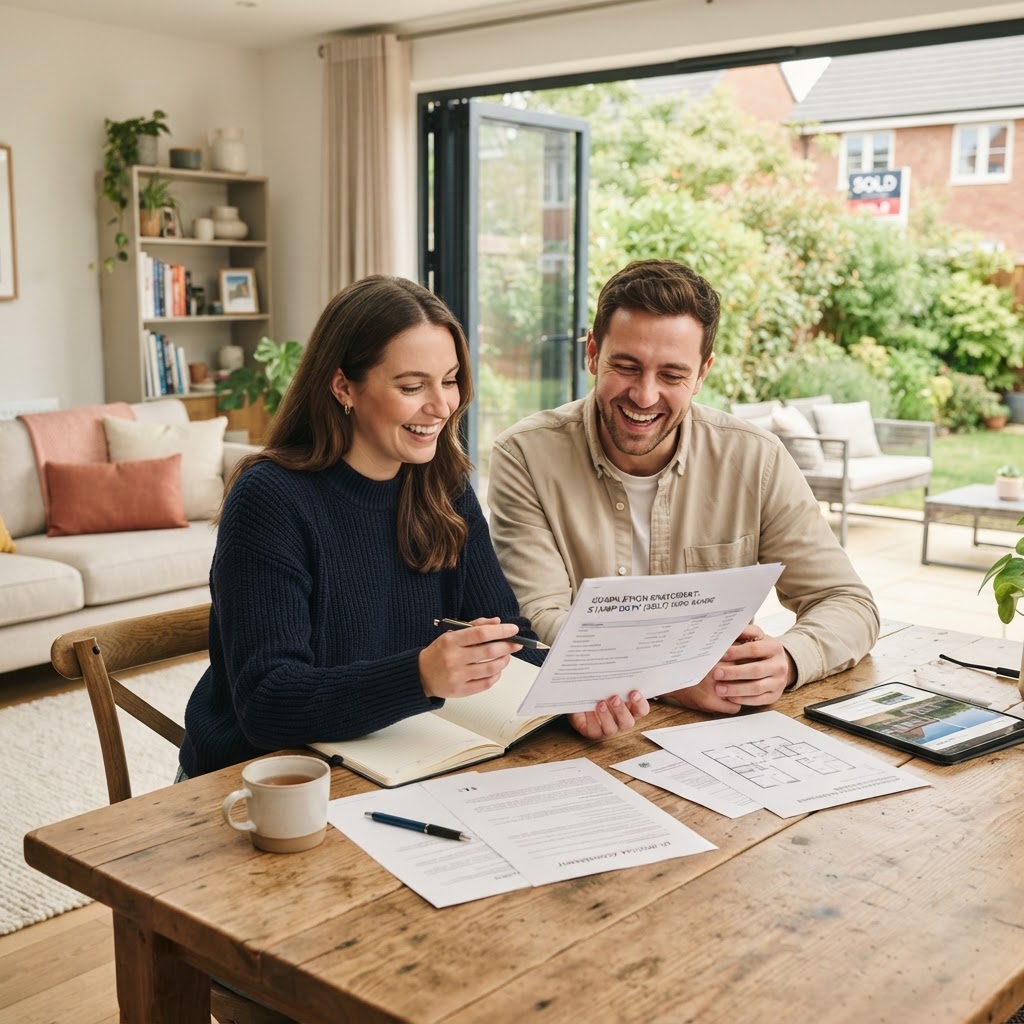
Understanding Stamp Duty: A 2026 Homebuyer's Guide
Introduction: Managing Your Moving Costs
Buying a home is one of the most significant financial commitments you will ever make. Beyond the deposit and monthly mortgage repayments, understanding the additional costs—specifically Stamp Duty Land Tax (SDLT)—is essential for accurate budgeting. With the current economic landscape, being prepared for these one-off expenses can prevent unwelcome surprises during the conveyancing process.
In this guide, we break down how Stamp Duty works in the current 2026 market. Whether you are a first-time buyer or looking to move up the property ladder, knowing your tax obligations is a vital step in your journey. We will explore the latest thresholds and how they apply to your specific situation.
What is Stamp Duty Land Tax?
Stamp Duty is a tax paid to the government when you purchase a residential property in England or Northern Ireland above a certain price threshold. It is a progressive tax, meaning you pay different rates on different portions of the property price. Understanding these bands is crucial because they determine the total amount you need to set aside before completion.
It is important to remember that Stamp Duty is not a flat fee; it is calculated based on the purchase price of the property. While the Bank of England base rate currently sits at 3.75% and inflation is at 3.1%, these broader economic factors influence the housing market, but your tax liability remains tied to the specific value of the home you are purchasing.
First-Time Buyer Reliefs and Thresholds
For those entering the market for the first time, the government provides specific reliefs to help ease the financial burden. As of October 2026, first-time buyers can benefit from significant exemptions on Stamp Duty for properties up to a certain value. This relief is designed to make the initial step onto the property ladder more accessible.
- Up to £300,000: First-time buyers typically pay 0% Stamp Duty on properties in this price bracket.
- £300,001 to £500,000: You will pay 5% on the portion of the price within this range.
- Above £500,000: First-time buyer relief is generally not applicable, and standard residential rates apply to the entire purchase price.
Always verify your eligibility with your solicitor, as specific conditions apply to these reliefs. Ensuring you meet the criteria early in your search can help you refine your budget and focus on properties that offer the best value for your circumstances.
Practical Tips for Budgeting
When calculating your total moving costs, do not focus solely on the mortgage rate. While current average fixed rates are influenced by market volatility, your upfront costs—including legal fees, surveys, and Stamp Duty—are fixed expenses that must be paid at completion. Failing to account for these can lead to a shortfall in your available cash.
- Use an official calculator: Always use the official government or reputable financial guidance websites to estimate your tax liability. These tools are updated to reflect the latest 2026 thresholds.
- Factor in other costs: Remember that Stamp Duty is just one part of the puzzle. Budget for conveyancing fees, valuation costs, and potential home repairs to ensure your first year of homeownership remains stable.
- Consult a professional: If you are unsure about your tax status or how a specific property purchase might be taxed, speak to a qualified mortgage adviser. They can help you model your total costs and ensure your mortgage application aligns with your overall financial plan.
Next Steps
Navigating the complexities of property taxes and mortgage affordability can feel overwhelming, but you don't have to do it alone. Whether you are calculating your total moving costs or looking for the best mortgage deal in the current market, our team is here to help. Chat with Molly or speak to one of our expert advisers today for personalized guidance tailored to your unique financial situation.
Important Notice: The information in this article is for general guidance only and does not constitute regulated financial advice. Mortgage rules and rates change frequently. Always consult with a qualified mortgage adviser who can assess your individual circumstances and provide personalised recommendations. Your home may be repossessed if you do not keep up repayments on your mortgage.
Important Notice
This article provides generic mortgage information only and does not constitute regulated financial advice. Mortgage decisions should be based on your personal circumstances. Always consult a qualified FCA-regulated adviser before making mortgage decisions.
Need Personalised Advice?
Chat with Molly for instant guidance, or speak to a qualified Mortgage321 adviser for tailored recommendations.
Where to go next
The pages that go deeper on this topic.